Why Insurance Brokers and Insurance Marketing Firms Need ERP Software
Introduction: Why Insurance Intermediaries Need a Modern ERP
The insurance distribution industry is built on relationships, accurate records, timely service and coordinated work across many teams. An insurance broker may manage enquiries from individuals and businesses, compare suitable insurance options, coordinate quotations, collect documents, support policy issuance, assist with endorsements, follow up on renewals and help customers navigate service requests. An Insurance Marketing Firm (IMF) may have its own permitted distribution model, personnel, insurer relationships, customer records and operational responsibilities. As these activities grow, spreadsheets, personal email inboxes, paper files and disconnected applications can become difficult to control.
This is where insurance broking software and insurance ERP software can provide a more structured way of working. An enterprise resource planning platform connects business functions through shared data, workflows, reporting and permissions. For an insurance intermediary, that may mean connecting an insurance CRM, lead management, policy administration, renewal tracking, POSP or agent management where applicable, commission reconciliation, finance workflows, employee task management, document storage and analytics.
Buy Solution AI can use this topic to explain the business case for connected insurance technology. The key message is not that every intermediary must purchase the largest possible software package. Rather, a broker or IMF should evaluate where manual work, repeated data entry, missed follow-ups, fragmented records and weak visibility create material operational risks. ERP capabilities should be selected to solve those specific problems and scaled as the organization grows.
This article explains why brokers and Insurance Marketing Firms may require ERP software, what features to evaluate, how insurance CRM and POSP software fit into a wider system, and how a technology project can be planned responsibly. The term “ERP” is used here to describe an integrated operational platform; exact modules and regulatory requirements depend on the intermediary’s business model, permissions, contracts and implementation.
1. What Is ERP Software for Insurance Brokers and IMFs?
Enterprise resource planning (ERP) software brings multiple business processes into a coordinated system. In a general business, ERP may connect customer operations, finance, human resources, procurement, inventory and reporting. For an insurance intermediary, the relevant processes are different: leads, customers, policy records, renewal activities, employee tasks, insurer coordination, distributor networks, commission records and servicing workflows.
Insurance ERP software is not necessarily a single universal product. It may be a platform with modules, a CRM integrated with finance and document tools, or a collection of connected applications that share data through APIs. The right architecture depends on the size of the business, the complexity of its operations, existing systems, data sensitivity and budget.
An insurance broker management software platform may include customer relationship management, insurance lead management software, policy management, quotation tracking, document workflows, renewal reminders, commission reconciliation and management dashboards. An IMF management system may additionally require configurable workflows for its permitted distribution model, its Insurance Sales Persons (ISPs), insurer relationships and internal controls. A POSP distribution business may need POSP onboarding software, training and certification status tracking, agent productivity tools and commission reporting, where relevant to its model.
A connected insurance management platform helps create a common operational view. For example, when a customer enquiry becomes a qualified lead, the assigned employee can record the requirement, track the quotation process, attach supporting documents and create future follow-up tasks. If a policy is subsequently recorded, the system can associate the policy with the customer and create a renewal task based on the recorded expiry date. Managers can review activity and exceptions without asking every team member to prepare separate spreadsheets.
ERP should not be confused with an insurer’s core policy administration system. An intermediary’s ERP typically supports its own distribution, customer servicing and business operations. Insurer underwriting, premium calculation, issuance, claims decisions and other insurer-controlled processes remain with the insurer or authorized service provider unless an approved integration explicitly supports a particular action.
2. Why Insurance Brokers Need ERP Software
Insurance brokers coordinate a range of tasks between customers and insurers. A business may handle individual policies, commercial accounts, multiple product categories, renewal portfolios and service requests at the same time. When the number of customers, employees, branches or policies grows, informal processes can create avoidable delays.
The first reason to consider insurance broking software is operational visibility. A centralized system can show which enquiries are new, who owns each lead, which quotations are pending, which documents are missing and which customer requests require action. Without that visibility, managers may rely on messages, phone calls and manual reports to understand what is happening.
The second reason is consistency. An insurance CRM can define standard stages for lead qualification, customer discussions, quotation requests, proposal documentation, policy record updates and follow-up. Employees can follow a common process while still adapting to the customer’s needs. A consistent workflow also makes it easier to train new staff and identify process gaps.
The third reason is customer servicing. Insurance relationships continue after a sale. Customers may need copies of policy documents, help understanding administrative steps, reminders about renewal dates or guidance on how to contact the relevant insurer. Insurance policy management software and a customer service CRM can keep the history of requests, assigned tasks and outcomes in one place.
The fourth reason is renewal management. A renewal portfolio can become difficult to supervise when expiry dates are stored in different spreadsheets or employees’ personal calendars. Insurance renewal software can create a common renewal calendar, schedule reminders, assign follow-ups and display pending cases. It cannot guarantee renewal or coverage, but it can make the follow-up process more organized.
The fifth reason is financial reconciliation. Commission statements, policy records, insurer reports and distributor arrangements may need to be compared. Insurance commission management software can help record expected amounts, received amounts, adjustments, reconciliation differences and approved payouts. Clear status labels reduce the risk of treating estimated amounts as confirmed income.
The sixth reason is management reporting. An insurance broker management system can produce reports on lead sources, conversion rates, renewal follow-ups, service request volumes, workload, policy records and commission reconciliation. Better reporting can help leaders decide where to allocate staff, improve training or investigate bottlenecks.
Finally, a broker may need stronger access controls as it grows. Role-based permissions, audit logs, secure document storage and defined data retention practices help the organization manage sensitive customer and policy information. These controls must be configured, monitored and reviewed; purchasing software alone does not guarantee security or regulatory compliance.
3. Why Insurance Marketing Firms Need ERP Software
An Insurance Marketing Firm operates within a specific regulatory framework and must manage its business according to the activities it is authorized to undertake. Its technology should reflect that operating model rather than simply copying the configuration of a broker or insurer. IMF software can provide a common place to manage customer information, personnel workflows, leads, policy servicing records, renewal activity and operational reports, as applicable.
For an IMF, one challenge is coordination between customer-facing personnel and the back office. A lead may be generated by one team member, assigned to an authorized person, followed up by another employee for documentation and later monitored by an operations team for status updates. If the information is not shared consistently, duplicate records and unclear ownership may result. IMF CRM software can create assigned ownership, status history, task reminders and escalation rules.
A second challenge is personnel management. Depending on the IMF’s arrangements and requirements, the organization may need to maintain employee or Insurance Sales Person records, onboarding documentation, training or eligibility status and supervisor assignments. An IMF management system can make these records easier to locate and can flag incomplete administrative steps for review. The software should not be treated as proof that an individual is legally eligible; required checks and approvals must still be completed.
A third challenge is insurer and product coordination. An IMF may work within permitted arrangements and need clear records of which products, workflows or documents apply to a particular situation. Configurable product records and internal guidance can reduce confusion. Any feature that presents products or enables transactions should respect the IMF’s actual permissions and agreements.
A fourth challenge is policy and renewal tracking. IMF renewal management software can connect customer records to policy expiry dates and assign follow-up tasks. It can also help record whether a customer was contacted, whether documents are pending and whether the case requires escalation. Reminders should follow approved communication practices and customer preferences.
A fifth challenge is operational oversight. An IMF reporting dashboard can summarize leads, follow-ups, policy records, pending documentation, staff workload and service cases. Management can use these reports to review service quality and identify backlogs. Any regulatory reporting should be checked against the current official format and requirements rather than assumed to be complete merely because a report can be exported.
A sixth challenge is maintaining a defensible record of important actions. Access logs, approval histories and document version records can support internal review. They do not replace legal obligations, recordkeeping policies or professional advice, but they can make information easier to retrieve when questions arise.
For these reasons, a CRM for Insurance Marketing Firm operations should be assessed on more than lead tracking. It should be able to support the firm’s real workflow, permissions, customer service, personnel administration, document management and management reporting. The specific modules required will differ by firm and should be confirmed during requirements analysis.
4. ERP vs CRM: How the Systems Work Together
CRM and ERP serve related but different purposes. Insurance CRM software focuses primarily on customers, prospects, communications, sales opportunities and follow-up. ERP covers a wider set of business operations and may connect CRM with document management, finance, human resources, approvals, reporting and other processes.
A broker or IMF may start with a CRM because the immediate need is to organize enquiries and customer interactions. As operations grow, the business may require policy tracking, commission reconciliation, personnel management, branch reporting and standardized workflows. It may then extend the CRM through integrated modules or adopt a broader insurance enterprise software platform.
The important question is not whether ERP is always better than CRM. It is whether the business has processes that require shared records and cross-functional coordination. A small organization with simple workflows may be well served by a focused insurance CRM. A larger intermediary with several departments, branches, distributor groups and financial reconciliation needs may benefit from a more integrated platform.
A well-integrated system should avoid unnecessary duplication. Customer data should not need to be manually re-entered into every module. Policy records should connect to the correct customer. Renewal tasks should reference the relevant policy. Commission records should be traceable to source records and reconciliation status. Reports should use agreed definitions and access rules.
Integration does not mean every employee should see every record. Permissions should be designed around job responsibilities, and sensitive information should only be available to authorized users. Systems should also handle failed integrations, duplicate messages and data corrections through controlled procedures.
5. Essential Insurance ERP Modules
A practical insurance ERP project begins with a module map. The following modules are common areas to evaluate; they are not a claim that every software product includes all of them.
Customer and CRM module: stores customer profiles, contact details, interactions, enquiries, preferences and assigned relationship owners. It supports insurance customer relationship management, customer segmentation, follow-up and service history.
Lead management module: captures enquiries from approved sources, records campaign attribution, checks for possible duplicates, assigns leads and tracks pipeline stages. Insurance lead management software can create reminders for uncontacted leads and show conversion trends.
Policy management module: stores policy identifiers, insurer details, product category, relevant dates, premium information, documents and status history. Insurance policy management software should make it easy for authorized users to find and update records while retaining an audit trail.
Quotation and proposal workflow: records requests, required documents, quotation status and next steps. Any actual quotation generation or insurer submission depends on supported product configuration and approved insurer integration.
Renewal module: maintains expiry dates, reminder schedules, assigned follow-ups, customer responses and renewal status. Insurance renewal automation should not send communications without appropriate configuration and authorization.
Document management module: stores or links policy documents, customer-submitted forms, internal checklists and correspondence. It should support access controls, secure retrieval, version management and appropriate retention.
Commission and reconciliation module: tracks expected, reported, received, adjusted, reconciled and paid amounts. Insurance commission tracking should make calculation rules and source records visible to authorized staff.
POSP or agent management module: where relevant, maintains personnel profiles, onboarding steps, training records, eligibility status, team assignments, activity and performance reports. POSP management software must reflect the organization’s permitted distribution model.
IMF operations module: where relevant, supports IMF-specific personnel, customer, workflow and reporting requirements. IMF CRM software should be configured against the firm’s actual operating model and current applicable requirements.
Employee and task module: assigns work, defines due dates, tracks status, manages approvals and escalates overdue tasks. It can support back-office coordination and service-level monitoring.
Finance and accounting integration: connects relevant financial records to an accounting system or authorized finance workflow. The exact accounting functionality may be native or provided through integration.
Analytics and reporting module: produces management dashboards and scheduled reports with consistent definitions. Reports should allow appropriate filters without exposing records to unauthorized users.
Security and administration module: manages user roles, authentication, access review, audit logs, backup and recovery settings, integration credentials and system configuration.
Customer or distributor portal: provides secure access to permitted information and tasks. A portal should expose only the functions appropriate to the user’s role and the implementation’s supported capabilities.
6. Insurance CRM: Managing the Full Customer Lifecycle
The customer lifecycle starts before a policy is purchased and continues throughout the relationship. An insurance CRM helps organize this journey in a structured way.
At the enquiry stage, the CRM records where the enquiry came from, what the customer is seeking and which team member owns the next step. Lead source information helps the organization understand which marketing channels produce useful enquiries. Data collection should be limited to what is necessary for the stated purpose.
During qualification, an employee records the customer’s requirements and identifies what information is missing. The CRM can create tasks for a call, meeting or document request. Product suitability and insurance advice must remain with appropriately authorized personnel and should not be reduced to a simplistic automated score.
During quotation and proposal coordination, the CRM tracks the status of required documents and insurer communication. It can flag cases that have been waiting too long or require customer clarification. The system should clearly distinguish a draft, a submitted request, an issued policy and a completed transaction.
After issuance, the customer profile can link to the policy record and relevant documents. Service requests can be logged with categories, priorities, owners and status. A customer service CRM helps staff avoid losing the context of earlier interactions.
During the policy period, the system can track permitted service activities and customer communication preferences. As expiry approaches, renewal reminders can generate tasks for authorized employees. When the customer responds, the team records the outcome and updates the status.
After a service request is completed, the CRM can record the resolution and invite feedback where appropriate. Over time, management can review recurring service issues, renewal patterns and workload.
This lifecycle view makes insurance CRM more useful than a contact list. The objective is to maintain reliable context, clear ownership and timely next actions while protecting customer information.
7. POSP Software and Distributor Management
Organizations that use a POSP distribution model may need a specialized set of tools in addition to general CRM functions. POSP software can help coordinate onboarding, training records, lead allocation, sales activities and reporting, subject to the relevant intermediary’s authorization and operating arrangements.
The onboarding workflow may collect required details, documents and acknowledgements. It should display missing items and the current review status rather than silently marking an incomplete record as approved. Training and certification tracking can record the status of required steps, dates and supporting evidence where applicable.
After onboarding, POSP agent management software can provide a permitted view of assigned leads, pending tasks, customer follow-ups and relevant product resources. A supervisor may see team-level activity, while each POSP sees only records appropriate to their role. This division of access is important when multiple distributors operate within one network.
The system may record the status of quotation requests, proposal documentation and policy updates where those workflows are supported. It should avoid implying that every POSP can perform every transaction or sell every product. Permissions and product access should reflect the applicable rules and agreements.
Commission reporting can help distributors understand the status of recorded business and approved payouts. Clear labels should separate estimated commission from insurer-confirmed amounts and final approved payouts. Disputes or discrepancies should have a documented review process.
Mobile access is valuable for field teams, but mobile functionality should be designed with security in mind. Session controls, protected document access, limited local storage and appropriate authentication can reduce exposure if a device is lost or shared.
POSP reporting should focus on useful measures such as assigned leads, completed follow-ups, pending documentation, training status and authorized business activity. Metrics should be interpreted fairly and should not encourage unsuitable sales or unauthorized communication.
8. Policy Records, Documents and Renewal Automation
Insurance businesses create and receive many types of records. A policy document repository helps authorized staff locate the correct document and connect it to the appropriate customer and policy. Without a structured repository, staff may waste time searching email attachments, personal folders or physical files.
An insurance document management system should define a consistent naming and indexing approach. Useful fields may include customer reference, policy reference, insurer, document type, relevant date, upload date, owner and review status. Access should depend on the sensitivity of the record and the user’s responsibilities.
Optical character recognition and AI document extraction may assist with reading selected fields from supported documents. However, extracted information should be validated before it is relied upon for important operational decisions. The system should retain a clear distinction between the original document and extracted data.
Renewal automation begins with accurate policy dates. A renewal calendar can show upcoming expiries and create tasks according to configured schedules. An example schedule could use reminders at 30, 15 and 7 days before expiry, but the actual timing should be selected based on the product, workflow, customer preferences and applicable rules.
Each renewal task should have an owner, due date, status and next action. Statuses might include not started, contact attempted, awaiting customer response, documentation pending, quotation requested, completed or closed without renewal. The terminology should match the business process and must not imply that coverage continues after expiry unless that is confirmed.
Automation can send alerts to internal teams and, where properly configured, customers through approved channels. Email, SMS and WhatsApp Business integration may be useful, but channel access, templates, consent, provider rules and costs must be checked.
Renewal dashboards can show the number of upcoming policies, completed follow-ups, unresolved cases and records missing essential data. These measures help managers focus on exceptions rather than manually reviewing every policy.
A renewal system is only as reliable as its underlying records. Organizations should regularly check for incorrect expiry dates, duplicates, missing policy numbers and inconsistent customer details. Renewal software should support correction and audit history rather than simply sending messages from unverified data.
9. Commission Reconciliation and Financial Control
Commission and remuneration processes can involve multiple records and timing differences. A broker, IMF or distribution organization may need to compare internal policy records with insurer statements, contractual arrangements, adjustments and actual receipts. A well-designed commission management software module helps make these differences visible.
The system should distinguish the stages of a commission record. An expected amount is not the same as an insurer-reported amount. A reported amount may not yet have been received. A received amount may still require reconciliation. An approved distributor payout may differ from gross commission because of the applicable agreement and permitted adjustments.
Useful features include importing supported statements, matching records by policy or transaction reference, flagging unmatched items, documenting adjustments, assigning reconciliation tasks and recording approval history. The system should preserve the source of each amount and the date on which it was recorded.
Commission reports can be filtered by insurer, product category, period, branch, distributor or status, subject to access rights. Managers can identify long-pending differences and allocate them for investigation. A payout dashboard should show which records are awaiting confirmation, review, approval or payment.
The software should not assume a universal commission rate or automatically infer a payout entitlement from a policy premium. Applicable agreements, product rules, regulatory requirements and the intermediary’s actual arrangements must determine the calculation. Finance teams should validate rules and test edge cases before automation goes live.
An integrated platform can reduce repetitive spreadsheet work and make audit preparation easier, but it cannot eliminate the need for financial controls. Reconciliation responsibilities, segregation of duties, approval thresholds and periodic review remain important.
10. Lead Management, Marketing and Sales Workflow
Insurance lead management software helps businesses handle enquiries consistently from first contact through the appropriate sales outcome. Leads may come from a website, a referral, a campaign, an authorized partner or an employee. The system should record the source and the date received so the business can evaluate its marketing performance.
A lead workflow may include new, assigned, contact attempted, qualified, information pending, quotation requested, proposal in progress, converted and closed. The exact stages should reflect the organization’s actual sales process. Each stage should have a clear definition so that employees do not report the same activity differently.
Automatic assignment can use branch, territory, product category, workload or other transparent rules. Reassignment should retain history so that managers can understand who owned the lead at each stage. Duplicate detection can identify records that may refer to the same person, while allowing employees to review uncertain matches.
Follow-up automation creates tasks and reminders. Escalation rules can notify a supervisor when a lead remains untouched beyond a defined interval. These controls should support employees rather than encourage excessive customer contact. Communication frequency and channel must respect customer preferences, consent and applicable requirements.
Sales dashboards can show lead volume, contact rates, conversion by source, time in each stage and the number of pending tasks. Conversion rates should be calculated consistently and interpreted alongside quality and customer outcomes. A high lead count alone does not prove that a campaign is valuable.
Insurance marketing CRM can also help coordinate campaign records, approved content, referral tracking and customer preferences. The platform should avoid collecting unnecessary data or sending messages to people who have not consented where consent is required.
When lead management connects to policy management, the organization can see which opportunities become recorded policies and which require further action. This creates a more complete picture of sales operations.
11. Employee Operations and Workflow Automation
Insurance intermediaries rely on employees to coordinate documentation, customer support, sales administration, renewals, reconciliation and management reporting. When work is assigned informally, tasks may be duplicated or forgotten. Employee task management and workflow automation can improve visibility.
A task should normally identify an owner, due date, priority, relevant customer or policy reference, current status and next step. The system may support reassignment, escalation, comments and attachments. Sensitive documents should remain in controlled storage rather than being copied into unrestricted task notes.
Approval workflows can define which activities require review. For example, an adjustment to a financial record may require approval from an authorized manager. A document review task may require a second check before a record is marked complete. The exact controls depend on the organization’s processes and risk profile.
Operational dashboards can display overdue tasks, workload by team, average handling time and unresolved service requests. These measures can help managers rebalance work. They should not be used without context: a complex customer case may take longer than a routine administrative task, and quality should not be sacrificed for speed.
Automation may create a task when a policy document is uploaded, remind an employee when a deadline approaches or notify a supervisor when a request is stalled. Integrations should be tested for duplicate events and failures. There should be a way to identify tasks that were not created because an integration failed.
Standard operating procedures can be linked to workflows so that employees know which steps to follow. Training, permissions and change management are as important as the software itself. A system will not improve a process if employees do not understand it or if the underlying procedure is unclear.
12. Data Security, Privacy and Access Management
Insurance records may include contact details, policy documents, financial information and other sensitive data. An insurance ERP should be evaluated for security throughout its lifecycle, from implementation and migration through day-to-day use and eventual retention or deletion.
Role-based access control gives users only the access required for their work. For example, a sales employee may need to view assigned leads and relevant policy status, while finance staff may need commission reconciliation records. A manager may require team-level reporting but not unrestricted access to every sensitive document.
Authentication controls can include strong passwords, multi-factor authentication where appropriate, session expiry and account deactivation when a user leaves. Administrative accounts should be restricted and monitored. Access reviews should take place periodically and whenever job responsibilities change.
Encryption in transit and at rest, secure document storage, backup and recovery, vulnerability management and incident response procedures are important controls to evaluate. The organization should ask how data is hosted, who can access it, how backups are protected and what happens if a service provider experiences an incident.
Audit logs can record important events such as record access, changes, exports and approvals. Logs should be protected from unauthorized modification and retained according to a defined policy. They help with investigation but do not prevent every misuse.
Privacy management should cover the purposes for collecting data, access and correction requests where applicable, retention, deletion, vendor arrangements and lawful communication. The organization should assess the Indian data protection and sector-specific requirements applicable to its circumstances, including any relevant rules and commencement provisions.
Security claims should be specific and verifiable. A vendor should not be described as “fully compliant” solely because it provides encryption or audit logs. Compliance requires appropriate policies, controls, configuration, staff practices and ongoing oversight.
13. AI in Insurance ERP: Practical Uses and Limitations
AI can help insurance teams search information, process documents, draft routine communications and summarize operational activity. The most useful implementations begin with a defined task and a way to check the result.
AI-assisted document processing may extract policy numbers, dates, insurer names or selected coverage fields from supported documents. The system should show the source document and allow staff to correct errors. Poor image quality, unusual layouts and ambiguous wording can produce inaccurate results.
Natural-language search can help an authorized user locate a customer record or retrieve information from approved knowledge resources. The search must enforce the same access permissions as ordinary navigation. A user should not gain access to restricted information merely by asking an AI assistant.
AI-assisted customer support can draft answers to routine questions based on approved content. It should communicate uncertainty, avoid inventing policy terms and route complex or sensitive matters to a qualified employee. Customer-facing answers should not be treated as binding coverage determinations unless the relevant authorized process supports that function.
AI can summarize pending tasks, identify overdue follow-ups or group similar service requests. Such outputs can help managers focus attention, but the criteria should be transparent and reviewed for errors or unfair outcomes. A risk score should not automatically determine a customer’s eligibility or access to a product without a lawful and properly governed basis.
AI may assist with drafting reminders, internal notes and training materials. Human review remains important when communications could affect customer decisions or make representations about insurance products. Confidential customer data should only be sent to AI services under approved security, privacy and contractual arrangements.
Buy Solution AI can discuss AI insurance software as an opportunity for workflow assistance, but product marketing should clearly distinguish available features from proposed features. Prospective customers should ask for a demonstration, accuracy limitations, human-review controls, data handling details and a clear explanation of which systems are integrated.
14. Integrations, Data Migration and System Architecture
Insurance businesses often use several systems: accounting applications, email, messaging services, insurer portals, document storage, telephony and reporting tools. An insurance ERP project should identify which systems must exchange information and which can remain separate.
An API integration may transfer customer, policy or transaction information between supported systems. The implementation team should document what data is sent, which system is authoritative, how authentication works and what happens when a request fails. The existence of an API in one system does not automatically mean that another provider permits the required use.
Messaging integration may support approved email, SMS or WhatsApp Business workflows. Each integration may have separate setup requirements, templates, permissions, usage charges and rate limits. Payment or insurer integrations should be verified with the relevant provider and tested in an authorized environment.
Data migration is a major project step. Before importing old records, the organization should identify duplicate customers, missing dates, inconsistent policy references, obsolete contacts and incomplete documents. Data should be mapped to the new structure, cleansed where appropriate and tested using a representative sample.
A migration plan should include backups, access restrictions, validation totals, reconciliation checks, user acceptance testing and a rollback or recovery approach. The business should not assume that all historic data can be transferred perfectly. Some records may require manual review.
System architecture may be cloud-based, hosted privately or hybrid. The choice depends on scale, integration needs, security, availability, maintenance capability and cost. A cloud-based insurance software platform can reduce the need to maintain local infrastructure, but the organization still needs to assess service reliability, data residency where relevant, backup arrangements, contractual protections and exit options.
The project should also define ownership of configuration, data export formats, documentation and support. A vendor relationship is easier to manage when the customer knows how to retrieve its records and what happens if it changes providers.
15. Reporting, Analytics and Management Decisions
Management dashboards turn operational records into information that leaders can use. An insurance ERP can provide a consolidated view of activity across sales, servicing, renewals, personnel and financial reconciliation.
Useful CRM metrics may include new leads, time to first contact, lead stage distribution, conversion rates and source performance. Renewal metrics may include upcoming expiries, assigned follow-ups, contact completion and unresolved cases. Service metrics may include open requests, age of pending cases, resolution time and repeated issues. Financial metrics may include unmatched commission records, reconciliation status and pending approvals.
Metrics must have documented definitions. For example, a conversion rate could measure converted leads divided by qualified leads, or converted leads divided by all leads received. These are different measures. A dashboard should make the denominator and reporting period clear.
Reports should also identify data quality limitations. If expiry dates are missing or policy statuses have not been updated, a renewal report may be incomplete. A polished dashboard cannot compensate for unreliable source records.
Access should be controlled by role and business need. A branch manager may require branch-level reports, while a central finance role may need consolidated reconciliation data. Exporting reports should be monitored when they contain personal or commercially sensitive information.
Analytics should support questions, not merely display numbers. If renewal follow-ups are overdue, management may investigate workload, incorrect assignment rules, missing data or communication problems. If lead conversion varies by source, the team can examine lead quality and response time before changing marketing spend.
A reliable reporting process includes data validation, review cadence, ownership and documented definitions. This is more valuable than a large number of metrics that no one uses.
16. Common Challenges When Brokers and IMFs Operate Without ERP
Operating without an integrated platform does not mean a business cannot succeed. Many smaller organizations begin with spreadsheets and basic tools. Problems emerge when the process becomes too complex for those tools to manage consistently.
Fragmented customer information is one common challenge. Contact details may be stored in one spreadsheet, policy records in another and communication history in individual inboxes. Employees may not know which version is current.
Manual follow-up is another challenge. Renewal dates, callbacks and document requests can be missed when reminders depend on memory. A centralized task list can reduce this risk, although its value depends on accurate data and consistent use.
Duplicate data entry can waste time and introduce errors. If the same customer is entered into several systems, names, phone numbers or policy dates may differ. Shared records and validated integrations can reduce unnecessary repetition.
Unclear task ownership can cause delays. A customer may call several times because each employee assumes someone else is handling the request. Assignment, status and escalation features can make responsibility more visible.
Manual commission reconciliation can be difficult to audit. When figures are copied between spreadsheets without source references or approval history, it may be harder to explain a difference. A structured reconciliation workflow can make exceptions easier to investigate.
Management may also lack timely information. Preparing reports manually can take hours and may result in different teams presenting different totals. Shared definitions and automated reports can improve consistency.
Security can become harder to manage when documents are shared through personal accounts or broad-access folders. Central access controls and defined retention practices can reduce exposure, but they require ongoing administration.
The appropriate response is to map the actual problem before purchasing software. Some challenges may be solved through better procedures or a smaller CRM. Others may justify a broader insurance ERP.
17. How to Calculate the Business Case for Insurance ERP
A business case should compare the total cost of implementation with measurable operational benefits and risk reduction. Avoid assuming that software automatically produces a fixed percentage increase in revenue or productivity.
Start by documenting the current process. Estimate how much time employees spend entering customer information, searching for policy documents, preparing renewal lists, assigning leads, following up on missing documents and reconciling commission records. Use observed samples where possible rather than relying only on estimates.
Next, identify the process changes the proposed software will enable. For example, a shared policy repository may reduce document search time; automated task creation may reduce manual reminder preparation; reconciliation reports may help staff identify unmatched records faster. These benefits should be tested during a pilot.
Calculate implementation costs. Include licensing or subscription fees, configuration, data migration, integrations, training, support, internal project time, security review and ongoing administration. Consider additional costs for messaging usage, storage, custom reports or third-party APIs.
Choose a small number of measurable indicators. Examples include average time to locate a policy document, percentage of renewal tasks assigned before a defined deadline, number of duplicate records found, time spent reconciling statements and age of open service requests. Establish a baseline before launch.
After implementation, compare the results using consistent definitions and periods. If productivity improves, check whether the improvement is sustained and whether quality or customer outcomes have changed. A faster workflow is not beneficial if it increases mistakes or creates inappropriate customer contact.
The financial case may include time savings, reduced rework, improved reporting and better control. Potential revenue effects, such as higher renewal retention, should be treated as hypotheses to test rather than guaranteed outcomes.
A phased rollout often reduces risk. Start with one team or process, validate the results and expand only after the system proves useful. This approach gives the organization evidence for the next investment decision.
18. How to Select Insurance Broking Software or IMF ERP
Selecting software begins with requirements, not a feature checklist copied from a vendor brochure. The organization should document its business model, workflows, user groups, current tools, data volumes, integrations and security needs.
For an insurance broker, key requirements may include CRM, lead management, policy records, quotation tracking, renewals, servicing, commission reconciliation and branch reporting. For an IMF, requirements may include IMF-specific workflows, permitted personnel administration, insurer relationships and operational oversight. For a POSP network, requirements may include onboarding, training status, lead allocation, mobile access and distributor reporting.
Ask vendors to demonstrate complete workflows using realistic scenarios. For example, create a lead, assign it, record a customer interaction, attach a document, link a policy record, schedule a renewal task and show how the resulting activity appears in a management report. Ask what is native functionality, what requires customization and what depends on third-party access.
Review user permissions, audit history, data export, backup and recovery, incident response, service availability and support arrangements. Request clear documentation on hosting, data handling and vendor responsibilities. Do not rely on vague promises such as “bank-grade security” without supporting details.
Check scalability and usability. A system should be understandable to the people who will use it every day. Excessive complexity can lead employees to return to spreadsheets. Training and adoption planning should therefore be included in the project.
Compare total cost over a realistic period rather than comparing subscription prices alone. Include implementation, integrations, support, upgrades, additional users, data storage and exit costs. Ask how the business can export its data if it changes providers.
Finally, verify product claims. If the vendor advertises AI policy reading, insurer integrations, automatic commission calculations or customer portals, ask to see the feature in action and confirm its limitations. Buy Solution AI should use the same transparent approach when presenting its own software capabilities.
19. Implementation Roadmap for Insurance ERP
A phased implementation makes it easier to manage risk and build user confidence.
Phase one is discovery. Interview sales, operations, finance, servicing and management teams. Map existing workflows, identify bottlenecks and define the outcomes the project should improve. Separate mandatory requirements from desirable features.
Phase two is process design. Agree on customer and policy data fields, lead stages, renewal statuses, task ownership, approval rules and reporting definitions. Remove unnecessary steps before automating them.
Phase three is system configuration. Set up user roles, workflows, notifications, templates, dashboards and integration requirements. Keep access permissions aligned with job responsibilities.
Phase four is data preparation. Clean duplicates, standardize fields, validate policy dates and document references, and decide how historic records will be handled. Test migration with a sample before transferring the full dataset.
Phase five is integration and testing. Test supported connections, authentication, error handling, duplicate events, data synchronization and recovery. Test normal and unusual scenarios, not just the simplest workflow.
Phase six is user acceptance testing. Ask representative employees to complete real tasks and report issues. Confirm that the reports match source records and that users can perform their work without inappropriate access.
Phase seven is training and rollout. Provide role-specific training, short operating guides and a support channel. Start with a pilot team if practical, monitor problems and expand after key issues are resolved.
Phase eight is ongoing review. Track adoption, data quality, task completion and the project’s defined success metrics. Review permissions and integrations periodically. Maintain a backlog of improvements and assign an owner to each one.
The project should include a contingency plan and clear decision rights. ERP implementation is an operational change, not simply a software installation.
20. Common ERP Implementation Mistakes to Avoid
One mistake is automating a poorly defined process. If employees disagree about what a lead status means, automation will reproduce that inconsistency at a larger scale. Define the process before configuring triggers and reports.
Another mistake is migrating all historic data without reviewing its quality. Duplicates, obsolete contacts and incorrect expiry dates can undermine trust in the new system. Clean and validate data before relying on it.
A third mistake is attempting to launch every module at once. A broad rollout can overwhelm users and make it difficult to identify the source of problems. A phased implementation allows the organization to learn and adjust.
A fourth mistake is failing to assign ownership. Every important workflow needs a responsible person or team. Software can display a task, but it cannot decide who in the business is accountable unless the organization defines that rule.
A fifth mistake is ignoring permissions. Broad access may seem convenient during implementation, but it can expose sensitive records. Use least-privilege access and test user roles before launch.
A sixth mistake is over-automating customer communication. Too many reminders can annoy customers or breach channel requirements. Configure schedules carefully and maintain consent and preference records where required.
A seventh mistake is trusting AI output without review. Document extraction, summaries and generated answers can be wrong. Define when human verification is required and keep source information available.
An eighth mistake is measuring success only by login counts. Adoption matters, but the business should also measure process quality, time saved, data accuracy and customer outcomes.
Finally, organizations sometimes underestimate support and maintenance. Integrations change, user roles evolve and staff need training. Budget for ongoing administration and periodic review.
21. How Buy Solution AI Can Position Insurance ERP Solutions
Buy Solution AI can build a clear content and product narrative around the operational problems insurance intermediaries need to solve. Rather than claiming that a single system does everything, the company can explain how modules may work together and invite prospective customers to validate the required scope.
The main insurance broking software page can introduce the overall platform concept and link to dedicated pages for insurance CRM software, IMF CRM software, POSP management software, policy management, renewal automation, commission reconciliation and AI-assisted workflows.
The IMF page should focus on customer and personnel workflows, task ownership, policy tracking, renewal follow-ups, insurer relationship records and operational reporting, subject to the firm's authorized activities. The POSP page should explain onboarding records, training status, lead assignment, permitted sales workflows and distributor dashboards where supported.
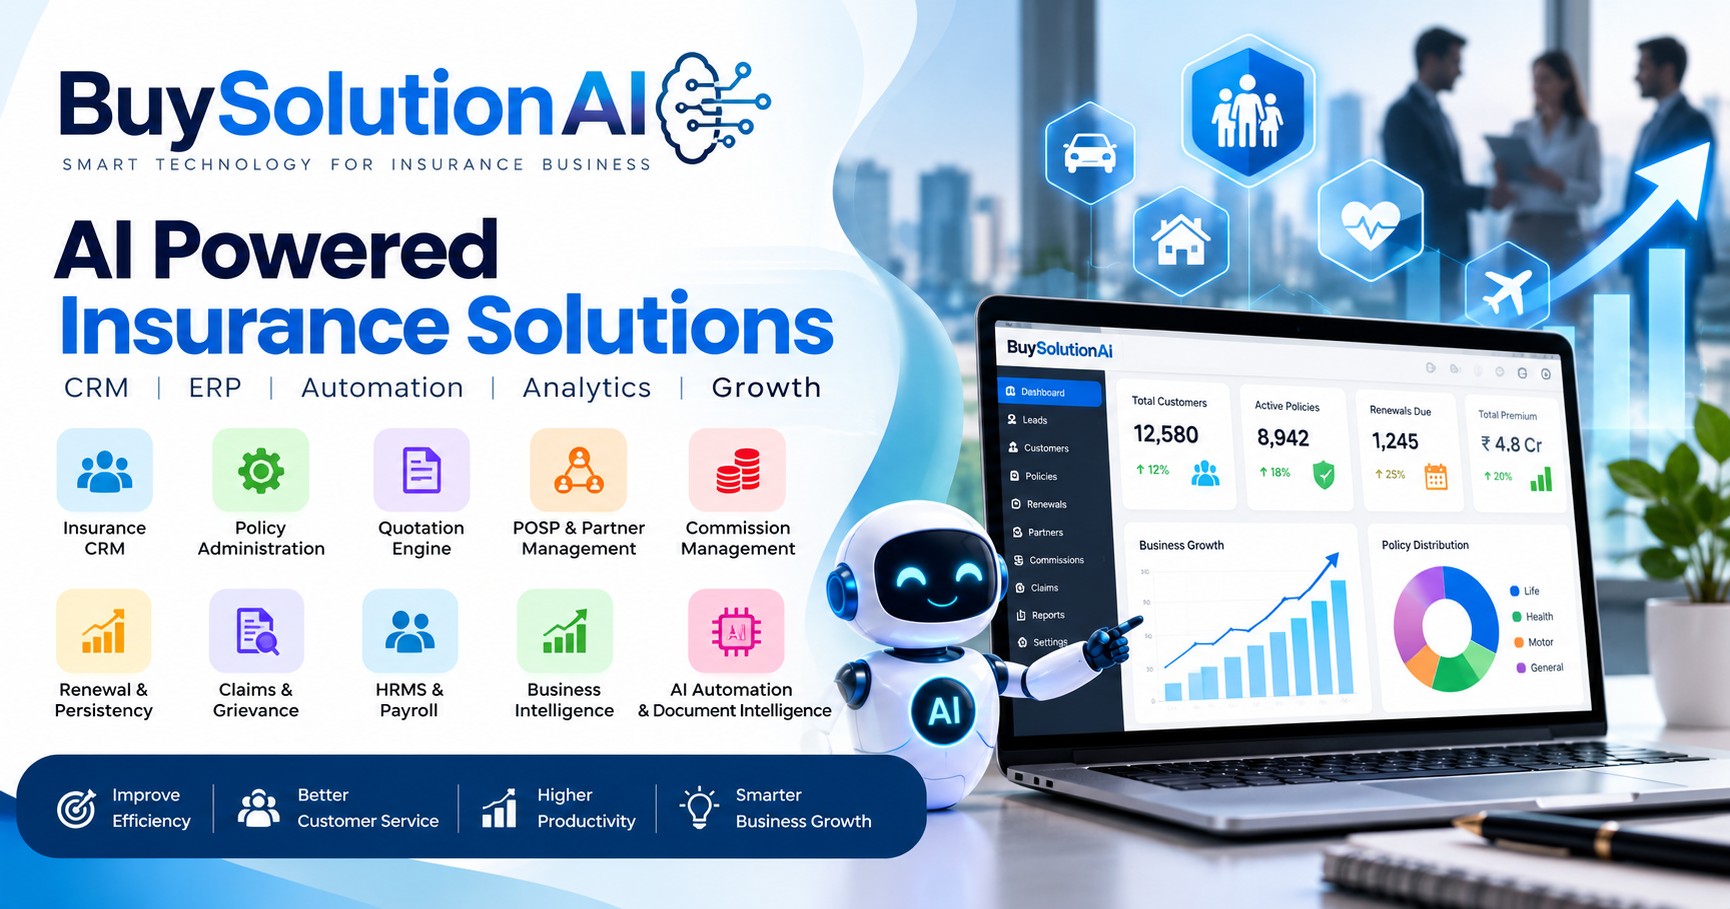
The CRM page can demonstrate customer profiles, lead stages, follow-up tasks, communication history and reporting. The renewal page can show how expiry dates become assigned tasks and how the team records outcomes. The commission page can explain the difference between expected, received, reconciled and approved amounts.
AI messaging should be specific. If the product supports document extraction or natural-language search, demonstrate the workflow and explain human review. If a capability is still planned, label it as a roadmap item rather than a current feature.
Buy Solution AI should provide clear product screenshots or demonstrations, implementation scope, integration details, security information and a way to request a consultation. Search content should answer genuine buyer questions instead of repeating the same keyword in every paragraph.
A useful commercial message is that insurance intermediaries can evaluate a connected operating model for customer management, policy records, renewals, personnel workflows and business reporting. The final module selection should be based on the customer’s needs, permissions and implementation plan.
22. Frequently Asked Questions About Insurance ERP Software
What is insurance ERP software? It is an integrated platform that can connect insurance CRM, policy records, renewal tracking, document workflows, commission reconciliation, employee tasks and reporting. The exact modules vary by product and implementation.
Why do insurance brokers need ERP software? Brokers may use ERP capabilities to coordinate leads, customer records, policy documents, renewal follow-ups, servicing, financial reconciliation and management reports. The value depends on the complexity of the broker’s workflows.
Why does an Insurance Marketing Firm need IMF CRM software? An IMF may need structured customer management, personnel records, lead assignment, renewal tracking, service workflows and operational reporting configured for its permitted business model.
What is the difference between CRM and ERP? CRM concentrates on customers, leads and interactions. ERP connects a wider range of operational processes. A business may use a CRM alone or integrate it with other modules as its needs grow.
What is POSP software? POSP software supports applicable personnel and distribution workflows such as onboarding, training records, lead management, task tracking and reporting, subject to the intermediary’s authorization and operating model.
Can insurance ERP automate policy renewals? It can track recorded expiry dates, create internal tasks and send configured reminders through supported channels. Automatic renewal, quotation or issuance depends on the relevant insurer process, authorization and integration.
Can ERP manage commissions? A commission module can record statements, expected amounts, receipts, reconciliation differences and approved payout status. Calculation rules must reflect the applicable agreements and requirements.
Does ERP replace insurer systems? No. An intermediary’s ERP usually manages the intermediary’s own customer and operational processes. Insurer-controlled underwriting, issuance and claims decisions remain with the insurer or an authorized service.
Can AI read insurance policy documents? AI may extract selected information from supported documents, but the results can contain errors. Important information should be validated against the source document.
Is cloud-based insurance software suitable for small businesses? It may be suitable when its cost, features, security, support and integration options match the organization’s needs. The business should evaluate total cost and exit arrangements.
Does software guarantee regulatory compliance? No. Software may support workflows and records, but compliance depends on permissions, policies, controls, staff practices, current requirements and ongoing oversight.
How should a broker select software? Map workflows, prioritize requirements, request realistic demonstrations, test integrations, review security and data export, compare total cost and plan training before deciding.
Conclusion: Build a Connected and Responsible Insurance Operation
Insurance brokers and Insurance Marketing Firms manage a connected set of customer, policy, personnel, renewal, financial and service activities. When these activities are spread across disconnected tools, the organization may struggle to maintain consistent records, clear task ownership and timely reporting. An integrated insurance ERP can help bring these workflows together.
For brokers, the business case often centers on customer relationship management, lead tracking, policy administration, renewals, servicing and commission reconciliation. For IMFs, the system should also reflect their specific permitted operating model and relevant personnel workflows. Where a POSP distribution network is involved, onboarding, training records, lead allocation and distributor reporting may also be important.
The right system is not necessarily the one with the longest feature list. It is the one that addresses real operational needs, protects sensitive information, supports the organization’s permissions, integrates with required systems and remains usable as the business grows.
Buy Solution AI can use this framework to help insurance intermediaries explore insurance broking software, insurance CRM, IMF CRM, POSP software, policy management, renewal automation and AI-assisted workflow options. Product claims should be verified through demonstrations, and each implementation should clearly define what is available, what requires configuration and what depends on third-party integrations.
The next step is practical: document the current workflow, identify the most costly or error-prone handoffs, select measurable outcomes and evaluate a focused pilot. With sound process design, reliable data and appropriate controls, insurance ERP software can become a useful foundation for more organized operations and better-informed decisions.
SEO Keyword Bank for Natural Use
Use these target phrases naturally in relevant sections, page titles, internal links, metadata and supporting articles. Do not publish them as a keyword-stuffed paragraph or hidden text.
Insurance Broking and ERP
insurance broking software; insurance broker software; insurance brokerage software; insurance broker management software; insurance broking management system; insurance intermediary software; insurance distribution software; insurance agency software; insurance agency management system; insurance business management software
insurance operations software; insurance administration software; insurance policy management software; insurance servicing software; insurance sales software; insurance workflow software; insurance business automation software; insurance software solutions India; insurance technology solutions India; insurance software company India
insurance software provider India; insurance management platform; digital insurance platform; insurance back-office software; insurance enterprise software; insurance software for intermediaries; insurance broker technology platform; cloud-based insurance software; online insurance management software; insurance software for startups
scalable insurance software
Insurance CRM
insurance CRM software; CRM for insurance agents; CRM for insurance brokers; CRM for insurance agencies; insurance customer relationship management; insurance customer management software; insurance lead management CRM; insurance sales CRM; insurance customer database software; insurance prospect management
insurance customer engagement software; insurance sales pipeline management; insurance CRM automation; insurance CRM dashboard; insurance CRM for small businesses; insurance CRM for distributors; insurance CRM for field sales; insurance customer retention software; insurance customer service CRM; insurance CRM with renewal reminders
insurance CRM with lead tracking; insurance CRM with policy management; insurance CRM with reporting; insurance CRM integration; cloud insurance CRM; AI insurance CRM; digital insurance CRM; insurance relationship management platform; insurance CRM workflow automation; insurance customer follow-up software
insurance contact management system; insurance sales tracking software; insurance enquiry management software
IMF CRM
IMF software; IMF CRM software; Insurance Marketing Firm software; Insurance Marketing Firm CRM; CRM for Insurance Marketing Firm; insurance marketing firm management software; IMF management system; IMF business management software; IMF operations software; IMF policy management software
IMF renewal management software; IMF customer management software; IMF distributor management software; IMF employee management software; IMF sales automation software; IMF lead management system; IMF onboarding software; IMF reporting dashboard; IMF business automation; insurance marketing workflow software
Insurance Marketing Firm digital platform; Insurance Marketing Firm technology solutions; Insurance Marketing Firm policy tracking; Insurance Marketing Firm renewal tracking; Insurance Marketing Firm operational dashboard; Insurance Marketing Firm servicing software; insurance intermediary CRM India; insurance sales person management software; ISP management software for IMF; IMF compliance workflow software
IMF insurer relationship management; IMF policy servicing system; IMF commission tracking software; IMF lead assignment software
POSP and Agent Management
POSP software; POSP management software; POSP insurance software; POSP agent management software; POSP CRM software; POSP onboarding software; POSP training management software; POSP certification tracking software; POSP lead management software; POSP policy management system
POSP commission tracking software; POSP payout management software; POSP sales dashboard; POSP mobile application; POSP insurance platform; POSP distributor software; POSP agent portal; POSP business management software; POSP workflow automation; POSP performance tracking
POSP renewal management; POSP customer management; POSP team management software; POSP reporting software; POSP digital onboarding; POSP document management; POSP sales tracking system; insurance agent management software; insurance agent CRM; insurance advisor management software
insurance distributor management software; insurance sales team management; insurance agent onboarding platform; insurance agent commission management; insurance agent productivity software; insurance agent portal software; insurance partner management software
Policy and Renewal
insurance policy management system; insurance policy tracking software; digital policy management; insurance policy document management; policy bond management software; insurance document repository; policy renewal software; insurance renewal management software; insurance renewal reminder software; automated policy renewal reminders
policy expiry tracking software; insurance expiry reminder system; insurance renewal CRM; insurance renewal automation; insurance renewal tracking system; motor insurance renewal software; health insurance renewal management; life insurance renewal tracking; insurance policy portfolio management; insurance policy record management
policy document storage system; insurance endorsement tracking software; insurance policy status tracking; insurance policy search software; insurance policy servicing platform; customer policy repository; insurance renewal follow-up system; insurance renewal calendar; insurance renewal pipeline management; insurance customer retention platform
policy lapse tracking software; insurance renewal workflow automation; digital insurance policy records; insurance document retrieval software; insurance portfolio tracking system
Leads, Sales, Commission
insurance lead management software; insurance lead generation software; insurance sales automation software; insurance lead tracking system; insurance lead assignment software; insurance sales pipeline software; insurance enquiry tracking; insurance prospecting software; insurance follow-up automation; insurance call tracking software
insurance sales dashboard; insurance conversion tracking; insurance campaign management software; insurance referral management software; insurance sales productivity tools; insurance quotation management software; insurance proposal tracking software; insurance application tracking system; insurance sales workflow automation; insurance marketing CRM
insurance customer acquisition software; insurance lead distribution platform; insurance sales performance analytics; insurance commission management software; insurance commission tracking; insurance commission reconciliation software; insurance commission calculation system; insurance commission reporting; insurance agent payout software; POSP payout tracking
insurance remuneration tracking; insurance financial reconciliation software; insurer commission statement management; insurance commission dashboard; insurance commission accounting software; insurance policy commission tracking; insurance distribution payout management; insurance payment status tracking; insurance finance operations software; insurance transaction management
insurance commission audit trail; insurance commission discrepancy reporting
AI, Integrations, Commercial
AI insurance software; AI-powered insurance CRM; artificial intelligence in insurance software; insurance workflow automation; AI insurance automation platform; insurance document automation; AI policy document reader; AI insurance document processing; intelligent insurance CRM; insurance customer support automation
AI insurance customer service; insurance chatbot software; AI insurance query assistant; automated insurance follow-ups; AI lead management software; AI insurance data extraction; insurance process automation; AI insurance analytics; insurance business intelligence software; AI insurance reporting tools
insurance task automation; insurance workflow management system; AI-assisted policy management; insurance knowledge management software; intelligent insurance document search; insurance data analytics platform; automated insurance renewal workflow; insurance customer portal software; insurance agent portal; insurance distributor dashboard
insurance employee dashboard; insurance mobile CRM; insurance cloud platform; insurance API integration; insurer API integration software; insurance messaging integration; insurance WhatsApp Business integration; insurance SMS reminder integration; insurance email automation software; insurance payment gateway integration
insurance complaint management software; insurance service request tracking; insurance role-based access control; insurance audit trail software; insurance data security software; best insurance broking software in India; insurance broking software provider in India; insurance CRM software for Indian brokers; affordable insurance CRM software; insurance broking software pricing
insurance broker software demo; POSP software provider in India; IMF CRM software in India; Insurance Marketing Firm software provider; insurance software with POSP management; insurance software with commission tracking; insurance software with policy renewals; insurance software with lead automation; insurance software with AI features; insurance software with customer portal
integrated POSP and insurance CRM; insurance distribution automation platform India; insurance operations automation platform; insurance technology platform for intermediaries; insurance business process management; insurance customer lifecycle management; insurance policy lifecycle software; insurance workflow digitization; insurance back-office automation
Recommended Internal Linking Structure
Main pillar page: Insurance Broking Software
Supporting page: Insurance CRM Software
Supporting page: IMF CRM Software
Supporting page: POSP Management Software
Supporting page: Insurance Policy Management Software
Supporting page: Insurance Renewal Automation
Supporting page: Insurance Commission Reconciliation Software
Supporting page: AI-Assisted Insurance Workflow Automation
Publishing and Accuracy Notes
Confirm every feature against the actual Buy Solution AI product scope before presenting it as currently available.
Distinguish native features from custom development and third-party integrations.
Use internal links only to pages that exist and are relevant.
Validate keyword search volume and intent using an SEO research tool; this keyword bank is a target list, not verified search-volume data.
Check current IRDAI requirements and applicable laws before making regulatory or compliance claims.
Add a clear call to action inviting readers to request a demo or discuss their requirements, if that service is available.
23. Industry-Specific Workflows: Motor, Health, Life and Commercial Insurance
Insurance intermediaries may work with several product categories, each with different information requirements and servicing patterns. An integrated insurance management platform should be flexible enough to organize these differences without suggesting that every workflow is identical. The exact activities available to a broker or IMF depend on its permissions, insurer arrangements and supported systems.
Motor insurance workflows may involve vehicle details, registration information, policy expiry dates, insured declared value or other product-specific fields, quotation requests, document checks and renewal follow-ups. A policy management system can associate these details with the customer and create a task when a recorded expiry date approaches. The platform should distinguish between information entered by a customer, data extracted from a document and information confirmed by an insurer.
Health insurance workflows may involve policy schedules, insured-member information, renewal dates, product documents and service requests. Because these records can be sensitive, access should be limited to staff with a legitimate business need. A customer portal may make authorized documents easier to retrieve, but the system should not expose medical or personal information to unrelated users.
Life insurance workflows can include policy records, premium schedules, nominee-related documents where appropriate, servicing requests and renewal or premium reminders where relevant to the product. The software should preserve the original policy document and avoid presenting a reminder as a guarantee that a policy will remain active if a premium is unpaid.
Commercial insurance may require account-level relationships, multiple locations, several policies, renewal planning and document coordination across departments. An insurance broker CRM can link related contacts, accounts and policy records while preserving the correct access rights. The platform can help employees identify pending documents and upcoming renewals across a portfolio.
Across all categories, a good system provides configurable fields, controlled status values, clear document links and reports that match the business process. It should not force every product into the same data model if that creates confusing workarounds. During implementation, the organization should map product-specific workflows, test examples and verify that users can distinguish confirmed facts from information awaiting validation.
24. Customer Experience, Retention and Service Quality
Insurance customers may interact with an intermediary at several points: when they first ask for information, when they compare available options, when they complete documentation, when they need a policy copy and when they require help with a service request. The quality of these interactions influences whether customers feel informed and supported.
Insurance CRM software can help create continuity between interactions. Instead of asking a customer to repeat the same information to every employee, authorized staff can review the previous contact history and the current status of the request. This should be done only through appropriate access controls and with respect for privacy.
Service-request management can classify enquiries, assign an owner, set an expected response target and record the resolution. If the request cannot be completed by the first employee, it can be escalated with the context attached. A clear status helps both staff and customers understand whether action is pending, in progress or complete.
Renewal reminders are another part of customer experience. A reminder should be timely, accurate and useful. It should identify the relevant policy and next step without implying that the customer is covered beyond the confirmed policy period. If contact preferences or consent requirements apply, the communication workflow should respect them.
A customer portal can offer access to permitted policy documents, renewal dates and service request updates. It should be accessible, mobile-friendly and understandable to people with different levels of digital confidence. A portal should also provide a route to human assistance when the customer cannot resolve an issue independently.
Customer retention metrics should be interpreted carefully. A system can measure recorded renewals or follow-up completion, but it cannot establish that every renewal was appropriate or that every customer received a suitable outcome. Managers should review feedback, complaints, service quality and the reasons customers do not renew.
A useful insurance customer retention platform supports consistent service rather than aggressive messaging. It helps employees know what needs attention and makes the customer journey easier to manage without replacing professional advice or insurer decision-making.
25. Governance, Auditability and Responsible Use
An insurance ERP should be supported by clear governance. The organization should define who owns customer data, who can change workflow rules, who approves financial adjustments, who manages integrations and who reviews access permissions. Without ownership, even a feature-rich platform can become unreliable over time.
Auditability means that important changes can be traced. Depending on the system, the audit trail may record who created or changed a customer record, when a policy date was updated, who approved a reconciliation adjustment and when a service request was closed. The organization should determine which events must be logged and how long records should be retained.
Workflow permissions should reflect segregation of duties where appropriate. For example, the person entering a financial adjustment may not be the only person who can approve it. An administrator who changes access settings should be accountable for that action. These controls should be proportionate to the size and risk profile of the organization.
Data quality governance is equally important. Customer records need defined formats, duplicate handling, validation rules and correction procedures. Policy expiry dates should have a reliable source. Commission records should link to source statements or other supporting evidence. Reports should indicate when data is incomplete.
Vendor governance should cover support arrangements, system availability, change management, security incidents, subprocessors where relevant, data export and exit planning. The organization should know how it will retrieve its records if a contract ends or a system is replaced.
AI governance should define approved use cases, prohibited uses, review requirements and escalation paths. AI-generated text should not be treated as an authoritative policy interpretation unless validated through an approved process. Staff should know how to report inaccurate outputs and how to correct the underlying information.
A governance framework does not need to be unnecessarily complex. Even a small organization can maintain a concise register of system owners, permissions, key workflows, integrations, retention rules and review dates. The important thing is that responsibility is explicit and controls are reviewed as the business changes.
26. A Practical ERP Readiness Checklist for Brokers and IMFs
Before selecting insurance ERP software, an intermediary can use a readiness checklist to clarify its needs and reduce the chance of purchasing an unsuitable system.
Business model: document the organization's legal and regulatory status, permitted activities, insurer relationships, distribution channels and service responsibilities. The software should be configured around the actual model rather than an assumed one.
Process map: write down how leads arrive, who qualifies them, how quotations are requested, how documents are collected, how policy records are maintained, how renewals are followed up and how service cases are closed. Identify repeated steps and common delays.
User groups: list employees, managers, finance users, branch staff, agents, POSPs or other personnel who need access. Define which information each group should view, edit, approve or export.
Data inventory: identify existing spreadsheets, databases, document folders, email archives and external systems. Record where the authoritative version of each data type resides and whether historic records need to be migrated.
Module priorities: separate essential modules from later enhancements. A first phase might focus on insurance CRM, policy records and renewal tracking. Commission reconciliation, distributor portals or AI-assisted document processing may follow once the core data is reliable.
Integration requirements: list the insurer systems, accounting tools, messaging channels, document stores and other applications that must connect. Confirm that each provider supports the required integration and identify the cost and approval requirements.
Security and privacy: assess authentication, role-based access, encryption, backup, logging, data retention, vendor access and incident response. Confirm how the organization will manage user departures and periodic access reviews.
Reporting: define the decisions managers need to make and the metrics required. Agree on definitions and identify the source records that support each metric.
Implementation resources: identify a project owner, process owners, technical contacts and staff who can participate in testing. Include time for data cleaning, training and post-launch support.
Acceptance criteria: define how the organization will know the system is ready. Examples include successful migration checks, accurate renewal dates in a test sample, correct access permissions, functioning task alerts and reconciled report totals.
Ongoing review: set dates to evaluate adoption, data quality, security settings, integrations and the benefits identified in the business case. This makes ERP an evolving operational capability rather than a one-time installation.
27. Glossary of Insurance ERP and CRM Terms
ERP: Enterprise resource planning software that connects multiple business processes through shared records, workflows and reporting.
CRM: Customer relationship management software focused on customer information, leads, interactions, sales opportunities and follow-up.
Insurance broking software: Software supporting the operational workflows of an insurance broker, such as customer management, policy records, servicing and renewals.
IMF CRM: A customer and operations management system configured for an Insurance Marketing Firm's actual permitted business model and workflows.
POSP software: Software supporting applicable point-of-sales-person onboarding, training records, lead management, task tracking and reporting.
Lead management: The process of capturing, assigning, qualifying and tracking potential customer enquiries.
Policy management: The organization of policy details, documents, dates, status and servicing history.
Renewal automation: Rules and workflows that create renewal reminders, tasks and follow-up records from stored policy information.
Commission reconciliation: The process of comparing recorded expected amounts with statements, receipts, adjustments and approved payment records.
Role-based access control: A method of granting permissions according to a user's role and responsibilities.
Audit trail: A record of selected system events and changes that helps authorized users review what happened and when.
API integration: A supported method for systems to exchange data or request actions through defined interfaces.
Data migration: The process of transferring records from existing systems into a new platform, including mapping, validation and reconciliation.
Workflow automation: Rules that create tasks, notifications, approvals or status changes when defined conditions are met.
AI-assisted document processing: Use of AI or related technology to extract or classify information from documents, with validation where required.
Business intelligence: Reporting and analysis that helps managers understand operational performance and make decisions.
User acceptance testing: Testing by representative users to confirm that the system supports real business tasks before launch.
Least privilege: The security principle that users should receive only the access needed for their responsibilities.
Data retention: Rules that determine how long information is kept and when it should be archived or deleted, subject to applicable obligations.
Customer lifecycle management: Coordinating customer interactions from initial enquiry through purchase, servicing, renewal and ongoing relationship management.
28. Search Intent and Keyword Placement for Buy Solution AI
Search intent should guide where each keyword appears. A person searching “insurance broking software” may be researching platforms, comparing capabilities or preparing to contact a vendor. The pillar article should explain the category, the problems it addresses and the modules to evaluate. A dedicated product page can then provide implementation details, screenshots, supported workflows and a demo enquiry route.
A person searching “IMF CRM software” is more likely to need information about Insurance Marketing Firm workflows. A focused IMF page should describe customer records, lead assignment, personnel administration, policy tracking, renewal follow-ups and operational reports. It should not simply repeat the general insurance broker page with the acronym changed.
A person searching “POSP software” may be comparing onboarding, training records, agent management, sales dashboards and commission tracking. A POSP page should make clear which functions are available and which depend on the organization’s authorization, third-party integrations or customization.
A person searching “insurance renewal software” is likely interested in expiry calendars, task assignment, reminders, renewal status and reports. The relevant page should explain how reliable policy dates, customer preferences and workflow ownership affect the value of automation.
Use the primary keyword in the title, introduction and a relevant heading when it reads naturally. Use close variations where they clarify the topic. Avoid placing every keyword in every section. Search engines and readers benefit more from complete explanations, clear page structure and useful internal links than from repetitive keyword insertion.
The keyword bank included with this article contains related phrases across insurance broking software, insurance CRM software, IMF CRM software, POSP software, policy management, renewal automation, commission reconciliation, AI insurance software and integrations. Treat these phrases as research candidates, not as proof of search demand. Use an SEO tool to validate volume, competition and intent before assigning them to pages.
A sustainable content structure could include one pillar article about insurance ERP for brokers and IMFs, followed by separate pages for insurance CRM, IMF CRM, POSP management, policy document management, renewal automation, commission reconciliation, AI-assisted workflow automation and insurance integrations. Each page should answer a distinct user question and link to related resources.
Buy Solution AI should only state that a feature is available when it has been implemented and can be demonstrated. For planned capabilities, use clear wording such as “planned,” “under development” or “available subject to integration,” as appropriate. Accurate product content helps buyers understand the offer and protects the credibility of the website.